Almost everyone who buys a second home in North Idaho has the same story. They came for a long weekend, stood on a dock or a trailhead, and started wondering what it would take to make that feeling a regular part of life.
The dream is real. So are the details that separate a second home you love from one that becomes a chore. Here is what I tell buyers before they write an offer.
1. Decide which North Idaho you want
"North Idaho" covers a lot of ground, and each corner has a different rhythm.
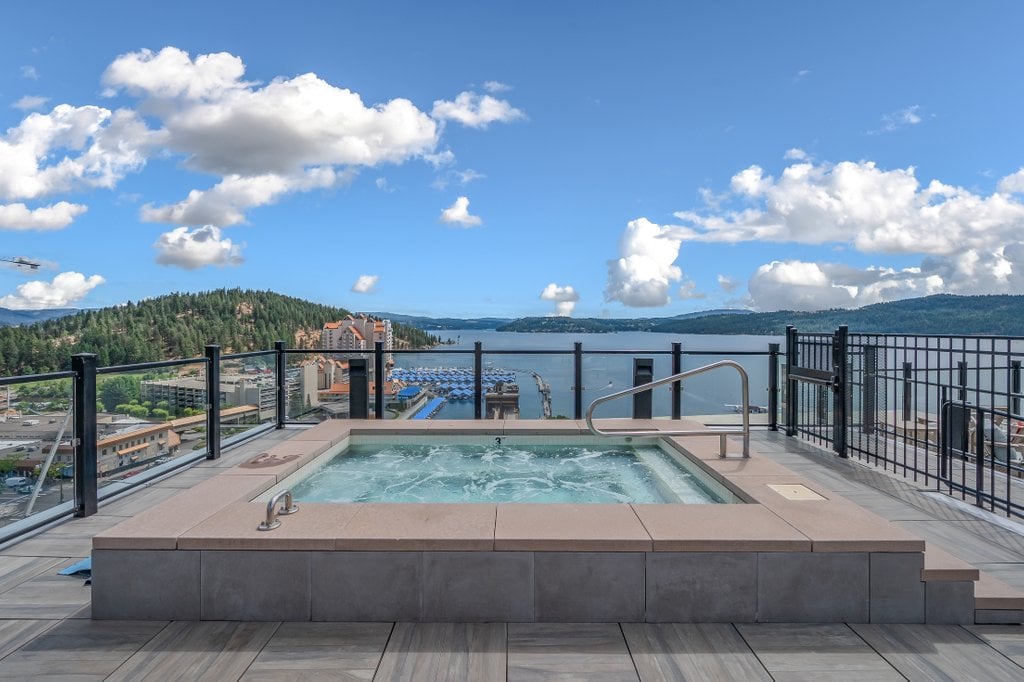
- Coeur d'Alene is the most convenient: a walkable downtown, the lake, a hospital, and quick access to the Spokane airport.
- Hayden and Hayden Lake trade some of the city energy for a quieter lake-town feel.
- Harrison and the south and east shores of Lake Coeur d'Alene feel more remote and a little slower.
- Sandpoint, Lake Pend Oreille, and Priest Lake sit farther north, with their own character, and Schweitzer Mountain nearby for skiing.
Before you start looking at listings, picture how you will actually use the place. A house you can reach in a quick drive from the airport and lock up for the week is a different purchase from a cabin that needs a long drive and a plan for the snow.
My advice: visit in the off-season before you buy. See the place in November or February, not just July. Winter tells you the truth about roads, light, and how much you will want to be there.
2. Financing a second home is its own category
Lenders treat second homes differently from primary residences. The details vary by lender, so talk to one early, but here is the general picture:
- Many lenders want at least 10% down, and borrowers with lower credit scores or higher debt often need 20 to 25%.
- A credit score around 680 or higher is typical, though some programs go lower with a larger down payment.
- Debt-to-income ratios generally top out around 45%.
- Expect to show cash reserves after closing.
- Rates tend to run a bit higher than for a primary residence, often by roughly a quarter to a half point.
Occupancy rules matter too. A second-home loan assumes you will use the property yourself, so it generally cannot be a full-time rental, and rental income usually cannot be counted toward qualifying. If you plan to rent it out heavily, you may be in investment-property territory, which has different terms. A lender can tell you which category fits your plan.
3. If you plan to rent it, check the rules first
Many second-home buyers hope the property can help pay for itself with short-term rentals. Rules vary by city and county, so verify before you assume.
In the City of Coeur d'Alene, for example, stays of 1 to 29 nights require a permit that must be renewed every year. The first-year fee is $285 and renewals are $180. Permits do not transfer from the seller to the buyer, so the new owner has to apply. Only one unit per parcel can be used as a short-term rental, and the owner or a responsible party must be reachable around the clock while guests are there. Stays of 30 days or longer are treated as ordinary rentals and do not need the permit.
Those rules apply inside city limits. Outside the city, in other cities, and in other counties, the requirements can be different. Ask before you buy, and do not rely on a previous owner's rental history as proof that the property can be rented.
4. Know how the property will be taxed
Idaho offers a homeowner's exemption that reduces the taxable value of a primary residence. It is generally tied to the home you live in as your main residence, so a second home typically will not qualify. The Kootenai County Assessor's Office can confirm how your situation would be treated.
Property taxes are only part of the picture. If you rent the home out, there are income tax questions as well. A local CPA who works with second-home owners can save you far more than they cost.
5. Do the due diligence that matches the setting
North Idaho properties are often in the trees, on hills, or by the water. That is the appeal. It also means a few extra questions:
- Water and septic. Is the home on a community system, a well, or city water? Is it on septic or sewer? Get inspections that fit what is actually there.
- Roads and snow. Is the road public or private? Who plows it and who pays? Can you get in during winter?
- Wildfire. Ask about defensible space around the house and talk to your insurance agent about coverage and costs.
- HOA and CC&Rs. Read the rules. They may affect rentals, building, parking, and what you can do with the lot.
- Internet and cell service. If you plan to work remotely, check this before you fall in love with the view.
- Shoreline and water rights. For waterfront property, confirm what you actually own and what you can build, such as a dock.
6. Plan for the months you are not there
A second home sits empty for long stretches, and a small problem can grow quietly. Before you close, line up:
- A local property manager or a trusted contact who can check on the house
- A winterization plan for plumbing and heat
- Insurance that fits a home that is sometimes unoccupied
- A plan for snow removal, yard care, and deliveries
Owners who set this up in advance enjoy their time there. Owners who skip it spend their visits fixing things.
7. A quick checklist
- Choose the area and test it in the off-season.
- Talk to a lender about second-home financing and your plans to rent.
- Check short-term rental rules for the exact address.
- Ask the county how the property will be taxed.
- Inspect for the realities of rural and lakeside living: water, septic, roads, wildfire.
- Read the HOA documents.
- Set up management, insurance, and winterization before you leave town.
If you are thinking about a second home in North Idaho, I would be glad to talk through what fits your plans. Reach out and let's start with how you want to spend your time here.
Lisa Biondo Coeur d'Alene Realty Windermere 208-699-3584
This post is general information, not legal, tax, or financial advice. Rules, fees, and lending terms change, so confirm the details with the city or county, your lender, and your CPA or attorney.
Sources